SME Lorry Financing Malaysia: First Time Buyer Guide to Grants, Loans, Hire Purchase, Eligibility and Application
SME lorry financing Malaysia helps small business owners buy their first commercial lorry through hire purchase, business loans, asset financing, development bank schemes, and guarantee supported financing. The right choice depends on your business age, cash flow, lorry price, deposit, and repayment strength.
Many business owners search for grants first. In practice, SME lorry financing Malaysia often comes from loans, hire purchase, or government guarantee schemes instead of direct cash grants. A good plan compares all options before you sign any agreement.
What SME Lorry Financing Malaysia Means for First Time Buyers
SME lorry financing Malaysia refers to funding used by a small or medium enterprise to buy a lorry for business use. The lorry might support delivery, construction, trading, agriculture, furniture moving, food distribution, cold chain, or logistics work. Your financing application should explain how the vehicle creates income, reduces rental cost, or improves delivery capacity.
A personal vehicle loan focuses on an individual borrower. SME lorry financing Malaysia focuses on a business borrower, business income, bank statements, company documents, and asset purpose. Banks and development finance institutions want to see that the lorry fits your business model.
SME Corp Malaysia defines manufacturing SMEs as firms with sales turnover not exceeding RM50 million or full time employees not exceeding 200. Services and other sectors fall under SME status when sales turnover does not exceed RM20 million or full time employees do not exceed 75. All SMEs must also register with SSM or equivalent bodies.
Reasons Need to Know SME Lorry Financing Malaysia Before Buying Their First Lorry
Many SMEs buy their first lorry when delivery demand grows, but paying cash reduces working capital. A lorry purchase also involves insurance, road tax, inspection, repairs, fuel, driver cost, and maintenance reserve. SME lorry financing Malaysia helps business owners spread the vehicle cost while keeping cash for daily operations.
The need is stronger when the business already meets SME status and has steady customer demand. SME Corp Malaysia defines SMEs by sales turnover or full time employees, with different limits for manufacturing, services, and other sectors. This makes proper business records important before applying for financing.
Commercial vehicle financing also fits SMEs because lorries are recognised business assets in hire purchase and asset financing products. Maybank lists commercial lorries, buses, prime movers, trucks, machinery, and industrial equipment under commercial and industrial hire purchase, with margin of finance up to 90% and loan period up to 5 years.
SME lorry financing Malaysia becomes a practical step when the lorry creates enough monthly income to cover repayment and running costs. SME Bank Vanigham Plus lists commercial vehicle financing margin up to 90% and tenure up to 7 years, subject to approval and policy. First time buyers should compare repayment, deposit, vehicle condition, and expected delivery income before choosing a lorry.
SME Lorry Financing Malaysia Grants, Loans, Hire Purchase and Guarantees
Grants
A grant sounds attractive because it suggests money without repayment. Direct grants for buying a lorry are limited and often tied to specific sectors, digitalisation, automation, green transition, export growth, or special programmes. Treat grants as one possible route, not the main plan. To learn more about available SME programmes, refer to SME Corp Malaysia’s programme and financing. SME Corp lists access to financing as one of its focus areas for SME support.
Business Loans
A business loan gives wider funding use. It can support working capital, asset purchase, stock, repairs, or expansion costs. SME lorry financing Malaysia through a business loan works better when you need both the vehicle and extra cash for insurance, fuel, driver cost, and early operating expenses. To learn more about SME financing access, refer to Bank Negara Malaysia’s SME financing and Fund for SMEs information. BNM provides SME financing information and participating financial institution guidance.
Hire Purchase
Hire purchase fits the asset purchase more directly. You choose the lorry, submit the quotation, and repay based on the approved financing structure. For many first time buyers, SME lorry financing Malaysia through hire purchase gives a clearer link between vehicle cost and repayment plan. To learn more about commercial vehicle hire purchase, refer to Maybank’s Commercial and Industrial Hire Purchase page. Maybank lists commercial vehicles such as passenger and commercial lorries, buses, taxis, prime movers, and trucks under its goods financed section.
Government Guarantees
Government guarantees support businesses with weak collateral. SJPP offers up to 80% guarantee coverage for financial institutions to assist Malaysian firms facing security hurdles. Similarly, CGC schemes improve financing access for MSMEs with limited track records or insufficient assets. For more details, refer to SJPP for government guarantee schemes and CGC for credit facilities tailored to MSMEs with limited collateral.
SME Lorry Financing Malaysia Eligibility Requirements
Before applying, prepare the key details that lenders usually check.
- SME status: Confirm that your business qualifies as an SME and has valid SSM registration or equivalent business registration.
- Business ownership: Prepare owner, partner, director, or shareholder details. Some schemes require Malaysian ownership or majority Malaysian shareholding.
- Operating history: Show how long your business has been active, what you sell or provide, and why a lorry is needed for daily operations.
- Income records: Prepare bank statements, sales records, invoices, accounts, tax documents, and existing loan details. Lenders use these to assess repayment ability.
- Lorry purpose: Explain how the lorry supports your business, including delivery routes, target customers, expected revenue, and current transport cost.
- Suitable lorry choice: Choose a lorry size and type that fits your business activity, budget, and repayment plan.
- Guarantee support: If you lack collateral, explore SJPP or CGC supported financing through participating financial institutions. These schemes help reduce bank risk, but repayment is still required.
SME Lorry Financing Malaysia Documents and Application Steps
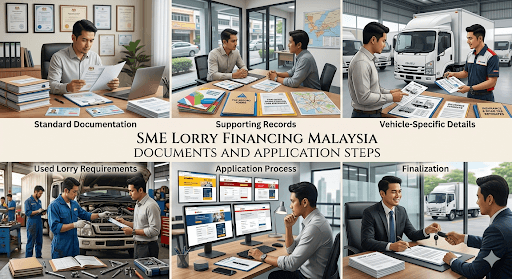
- Standard Documentation: Compile a strong file including SSM documents, owner/director IC copies, bank statements, financial accounts, and business licences.
- Supporting Records: Include company profiles, tax records, existing loan statements, and information regarding suppliers or customers.
- Vehicle-Specific Details: Provide quotations, model specifications, payload capacity, intended use, and estimates for insurance, road tax, and maintenance.
- Used Lorry Requirements: For used units, include inspection details and maintenance records, as repair costs significantly impact post-approval cash flow.
- Application Process: Select a lorry and budget, then compare facilities from commercial banks, SME Bank, MIDF, SJPP, and CGC.
- Finalization: Submit documentation, respond to queries, review offer letters, arrange insurance, and complete signing prior to vehicle collection.
SME Lorry Financing Malaysia With Eco R Truck Finance
For business owners who want a practical next step, Eco R Truck Finance offers financing support for commercial vehicle purchases through options such as hire purchase, leasing, balloon financing, and Islamic financing. Eco R Truck Finance also provides a truck finance calculator where buyers enter vehicle price, down payment, loan tenure, and interest rate to estimate monthly payments before applying. This helps first time buyers compare repayment affordability before choosing a lorry.
Eco R Truck Finance supports the SME lorry financing Malaysia journey with a practical loan calculator for first time buyers. Before applying, you can estimate your monthly repayment by entering the truck price, down payment, loan tenure, and interest rate. This helps you compare affordability, plan your cash flow, and choose a financing option that matches your business income before buying your first lorry.
Ready to finance your first lorry? Explore flexible truck financing options with Eco R Truck Finance.
SME Lorry Financing Malaysia JAC i40 EV Truck Financing Cost Planning Example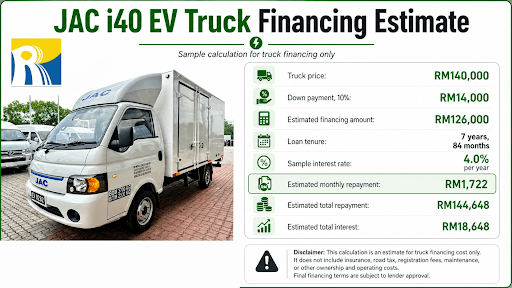
This example shows how truck financing works for a first time business purchase. It gives a simple view of the truck price, deposit, financing amount, loan tenure, interest rate, and estimated monthly repayment. Use it as a planning example to check whether the financing structure fits your business cash flow before applying. Learn more on JAC i40 EV Truck.
Disclaimer: This calculation is for estimated truck financing cost only. It does not include insurance, road tax, registration fees, maintenance, or other ownership and operating costs. Final financing terms are subject to lender approval. To learn more about truck financing options and try the calculator, visit Eco R Truck Finance.
Conclusion on SME Lorry Financing Malaysia
SME lorry financing in Malaysia must be treated as a business investment, not just a purchase. Compare options like grants, hire purchase, and bank loans, as each has different requirements for approval and repayment terms. For first-time buyers, the main goal is protecting cash flow. Ensure the lorry generates enough income to cover all ownership costs, including installments, insurance, maintenance, and driver costs.
A strong application requires a clear business purpose, stable income records, suitable vehicle selection, and a realistic repayment plan. The safest approach is to prepare documents early, compare financing options, and review the total cost before committing. Financing is most practical when the vehicle meets real business demand and avoids pressuring working capital.
FAQ on SME Lorry Financing Malaysia
- What should I check before applying for SME lorry financing Malaysia?
Check your business cash flow, monthly delivery demand, deposit budget, lorry type, and repayment ability. The lorry should support real business income, not create pressure on working capital. Prepare bank statements, SSM documents, vehicle quotation, and a simple cash flow estimate before contacting a lender.
- What if my business is new or has less than two years of operation?
A newer business may face stricter checks because lenders have less income history to review. Strengthen the application with recent bank statements, confirmed customer orders, invoices, delivery contracts, owner financial records, and a clear repayment plan. Some lenders may still review the case based on business potential and supporting documents.
- How do I know if the monthly repayment is affordable?
Compare the estimated monthly repayment with expected lorry income after fuel or charging, driver cost, maintenance, insurance, road tax, and emergency reserve. The lorry should leave positive cash flow after all major costs. Use a financing calculator first, then adjust the deposit, tenure, or truck budget if the repayment looks too high.
- What if I do not have collateral?
Look at guarantee supported financing through participating financial institutions. SJPP and CGC related schemes help businesses with limited collateral access financing, subject to approval. These schemes support the lender’s risk assessment, but the business still needs to repay the facility.
- Should I apply directly to a bank or through a truck financing provider?
Apply directly to a bank if you already know the financing product and have complete documents. Use a truck financing provider if you want help comparing vehicle choices, financing options, and estimated repayment in one place. For first time buyers, guided support may save time during document preparation and application review.
- What should I do after financing is approved?
Review the offer letter, financing amount, tenure, interest or profit rate, monthly repayment, late payment terms, insurance requirement, and ownership conditions. Confirm all extra costs before collecting the lorry. After purchase, track monthly income, installment payment, maintenance cost, and vehicle usage so the lorry stays profitable for the business.
- Does a first time buyer need a good credit score for SME lorry financing Malaysia?
Yes. Lenders usually review the owner or director’s credit record, business repayment conduct, bank statements, and existing commitments. A first time buyer with limited financing history should prepare stronger income records, clean bank statements, confirmed sales, customer orders, or delivery contracts to support the application.
Upgrade Your Business with Eco R Truck – Malaysia’s Leading Commercial Vehicle Dealer for Truck and Lorry
You can always explore more at Eco R Truck!
Eco R Truck is Malaysia’s premier commercial vehicle dealer, offering a wide selection of new, used, and rebuilt truck malaysia. From light-duty to heavy-duty models, we offer high-quality trucks that meet the diverse needs of businesses nationwide.
Ensure your business is equipped with reliable and efficient lorries and trucks with Eco R Truck’s comprehensive inventory and expert advice, you’ll find the perfect vehicle for your logistics, transportation, and delivery needs.
Follow Eco R Truck for Exclusive Offers:
- Access the latest truck models and specifications, including Hino, Isuzu, Mitsubishi, and more.
- Get expert advice on the best truck options for your business requirements.
- Join us for special promotions, updates, and exclusive deals on top truck models.
- Explore financing options and after-sales services that support your business growth.
Contact Eco R Truck Malaysia Today:
- Address:
Office: Lot 448 & 449, Jalan Kapar, Batu 1, 41400 Klang, Selangor
Yard: Lot 3200, Batu 3 1/4, Jalan Kapar, 41400 Klang, Selangor
- Email: [email protected]
- Phone: +6012-2290569
- WhatsApp for Inquiry: https://wa.link/ws6ncq
Visit Eco R Truck Malaysia’s Social Media Profiles:
- Website: https://ecortruck.com.my
- Facebook: https://web.facebook.com/wesleygweefromsendokgroup
- YouTube: https://youtube.com/@gweexiang?si=TPgD_ahzX-clQCPt
- Tiktok: https://www.tiktok.com/@wesleygwee_oe
Post Views:
96
You might also like
Arm-Roll RORO Truck Malaysia: What It Is and Why Waste Companies Use It
An Arm-Roll RORO Truck Malaysia buyer sees that almost every construction site runs on one core piece
Steel Tipper Vs Aluminium Tipper Lorry Malaysia: Which Should You Buy For Your Industry
Choosing between a steel tipper lorry Malaysia buyers trust and an aluminium tipper lorry comes down
Volvo Electric Truck Malaysia: Cost, Range, And Fleet Fit Explained
Volvo Trucks Malaysia sells the first fully electric heavy duty prime movers in Southeast Asia, with
Isuzu D-Max 2026 Malaysia: Is The New 2.2 Turbodiesel Worth It For Business Buyers
A low purchase price does not automatically make a pickup the cheaper business asset. The Isuzu D-Max
Malaysia’s Most Trusted Commercial Vehicle Brands 2026: Top 7 Truck Brands Buyers Choose
Isuzu leads Malaysia’s most trusted commercial vehicle brands in 2026, with 6,880 truck registrations

How An XCMG Knuckle Boom Crane Works and What Capacity You Actually Need
A knuckle boom crane lifts and moves loads using a folding, jointed arm instead of one straight beam